


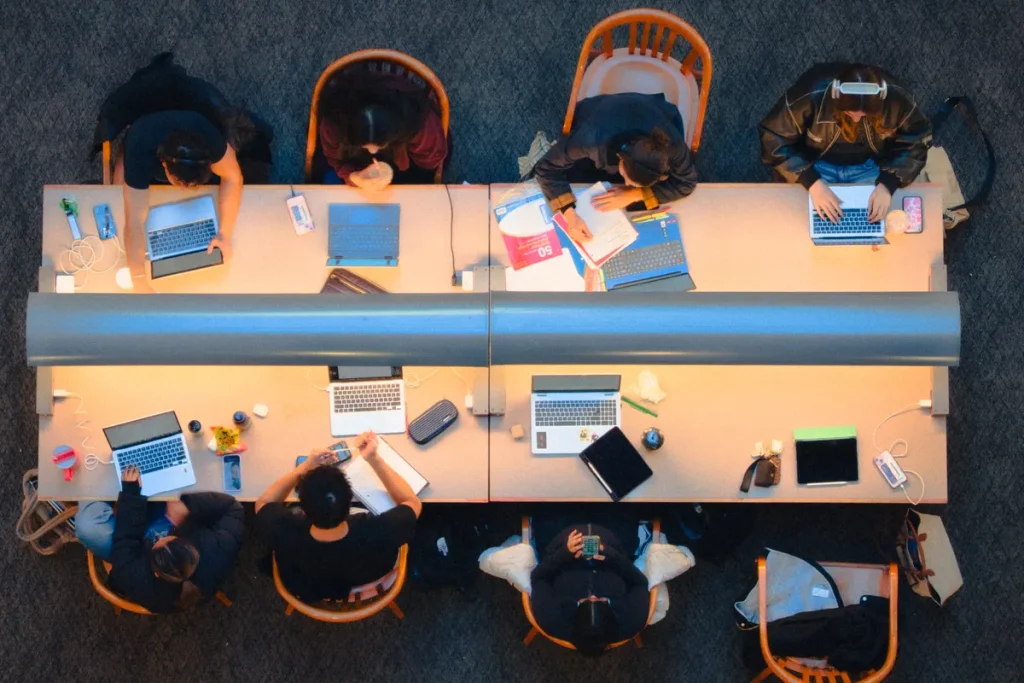

The cost of student insurance claims has doubled in three years, according to Aviva, and if that figure does not concentrate the mind of a freshers’-week-bound eighteen-year-old, the breakdown of what is getting stolen probably will.
Laptops and computers alone account for 40% of student possessions claims at Aviva. Mobile phones follow at 22%, with bicycles and bags/luggage/wallets each at 19%. Those four categories cover the overwhelming majority of claims before you even reach keys, jewellery, headphones, or games consoles.
My read is that students and their parents consistently underestimate the replacement cost of what goes to university. A laptop, a phone, a decent bike and a pair of headphones can easily clear £2,000 combined. The average claim doubling in three years suggests that students are arriving on campus with more expensive kit, and thieves are well aware of it.
What the student insurance claims data actually shows
The items are being taken from a wide range of locations. Insurance Today reported that Aviva identified theft locations ranging from break-ins to cars and student accommodation through to items stolen while students were travelling or socialising. The bar, the library, the train: nowhere is especially safe.
Steven Jackson, Aviva’s home product manager, made the point plainly: ‘Laptops, computers and mobile phones play a vital role in student life, but they can also be attractive targets for opportunistic thieves due to their value and portability.’ His practical advice runs from leaving expensive belongings at home to not using a laptop bag to reserve a café table. Both are sensible. Neither replaces insurance if something does go wrong.
On bikes specifically, Insurance Edge reported that Aviva offers up to £5,000 of pedal cycle cover for theft, loss or damage anywhere in the world, provided the bike is locked inside a building or secured to an immovable object. That conditionality matters: a bike locked only to itself, or to a fence that can be lifted, is unlikely to be covered.
Getting the cover right before term starts
The Association of British Insurers (ABI) recommends checking existing cover first. Some student halls include contents insurance; some parents’ home policies extend to children studying away. If neither applies, a standalone contents policy is the next step.
Two things catch students out. First, the single-item limit: a policy may cover £8,000 of contents overall but cap any one claim at £1,500, which is not enough to replace a high-end laptop. Second, out-of-home cover: standard contents insurance typically protects belongings inside the accommodation, not outside it. A phone stolen on the bus or a bike taken from a rack outside a lecture hall may not be covered unless you have specifically added that protection.
Creating a simple inventory, room by room, forces the sum. Add replacement costs for clothes, electronics and furniture, and you will almost certainly arrive at a higher number than you expected.
For anyone driving to university, there is a legal dimension. The ABI is clear that car insurance is compulsory, and if a parent’s vehicle is now being kept at a different address, the insurer must be told. If the student has become the main driver, that, too, requires disclosure. Failure to disclose is not a technicality: it can invalidate the policy entirely and, in the eyes of the law, constitutes driving without insurance.
The broader point is that student insurance claims are no longer a minor administrative exercise. A stolen laptop mid-semester is not just an expensive inconvenience; it is a disruption to coursework at the worst possible time. The data from Aviva suggests the financial exposure is larger than it has ever been. Getting the cover sorted before term starts, rather than after the first incident, is the only sensible order of operations.
